What Is a Short Sale in Texas? A Plain Guide for Owners
Maybe you heard the words "short sale" from a friend, a neighbor or a late night search, and it sounded like a way out. Sell the house for what it's worth, the lender takes the rest, and you move on. If only it were that simple.
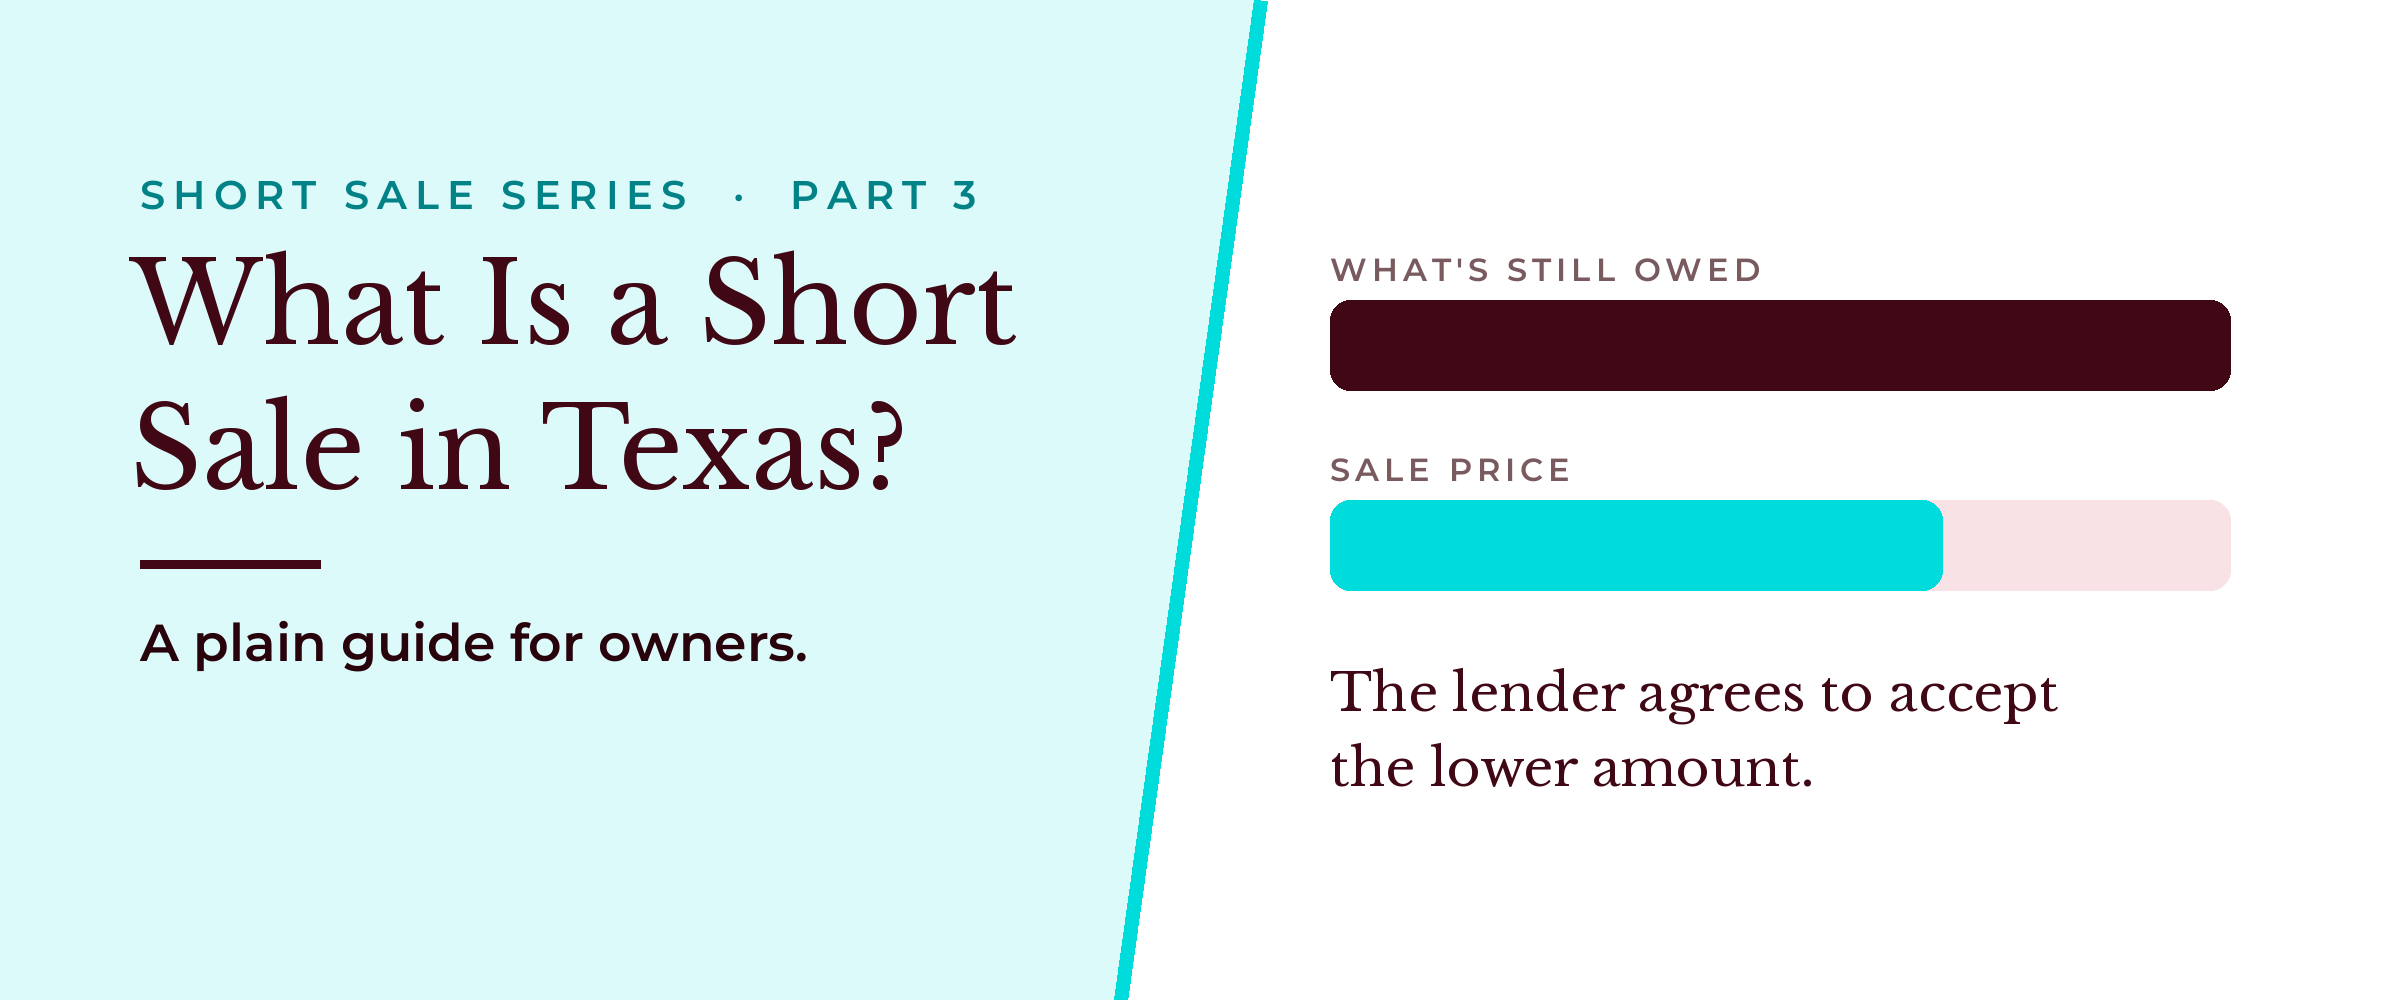
A short sale is when a homeowner sells for less than what's still owed on the mortgage, and the lender agrees to accept that lower amount. If you're a homeowner in Texas wondering what a short sale is, the short answer is that it's more involved than most people think, and lender approval is at the center of it.
(Part 3 of our short sale series)
What most homeowners don't realize about a short sale
Most people assume a short sale simply means selling a home for less than what's owed. That's the end result. Getting there takes more.
A short sale requires lender approval, a financial review and documentation showing why the situation exists in the first place. None of it is automatic, and it helps to know that before you count on it.
Why lender approval matters in a short sale
Think about it from the lender's side. They're being asked to accept less than the remaining mortgage balance, so they want the whole picture before they say yes.
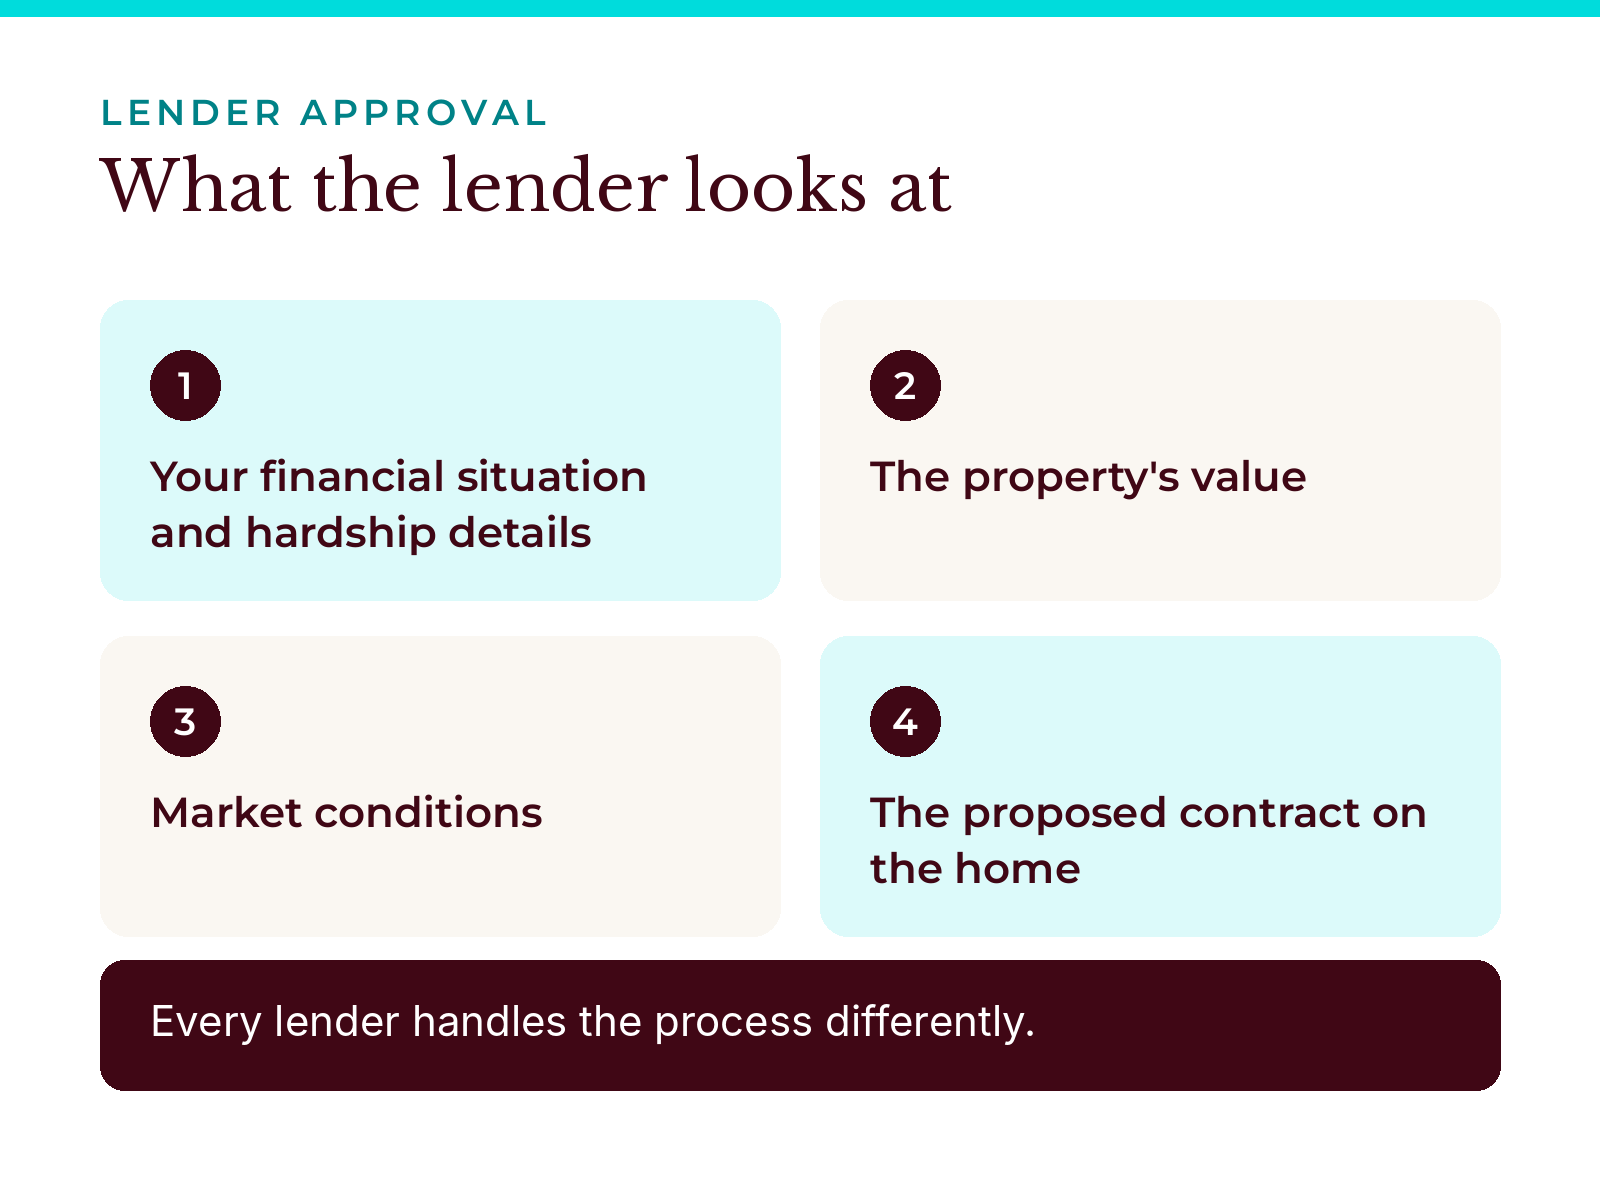
That means a close look at your financial situation and your hardship details, the property's value, market conditions and the proposed contract on the home. Every lender handles the process differently, which is one reason timelines and outcomes can vary.
Why some short sales fall apart
One of the biggest misconceptions is that every short sale gets approved. Some don't make it, and the reasons are rarely dramatic. Documentation was incomplete. Timelines got too tight. Communication broke down. Or expectations weren't set correctly from the beginning.
The earlier you understand the process, the better
Nobody plans for a short sale. But when life changes unexpectedly, knowing how the process actually works can ease a lot of confusion and pressure later. The earlier you have clarity, the easier it is to make informed decisions.
Short Sale FAQ
Is a short sale approved automatically?
No. The lender reviews your finances, hardship, the home's value and the proposed sale before deciding.
Who has to approve a short sale?
Your mortgage lender has to agree to accept less than the balance owed.
Can a Realtor answer legal or tax questions about a short sale?
Charles and I can walk you through the real estate side. For legal, tax or credit questions, please talk with an attorney, a tax professional or your lender.
Questions are welcome here
If you're a homeowner anywhere in the Greater Houston area and want to understand whether a short sale could fit your situation, reach out to us. We keep every conversation private.
Next in the series: The biggest mistake homeowners make before foreclosure (Part 4)
