Buying a home in Houston with your VA loan? Know your real payment before you shop.

Estimate your monthly payment with the VA funding fee, see how Texas disabled veteran tax exemptions lower your property taxes, and find out what makes a VA offer stand out with sellers.

Estimate my VA payment Texas veteran benefits
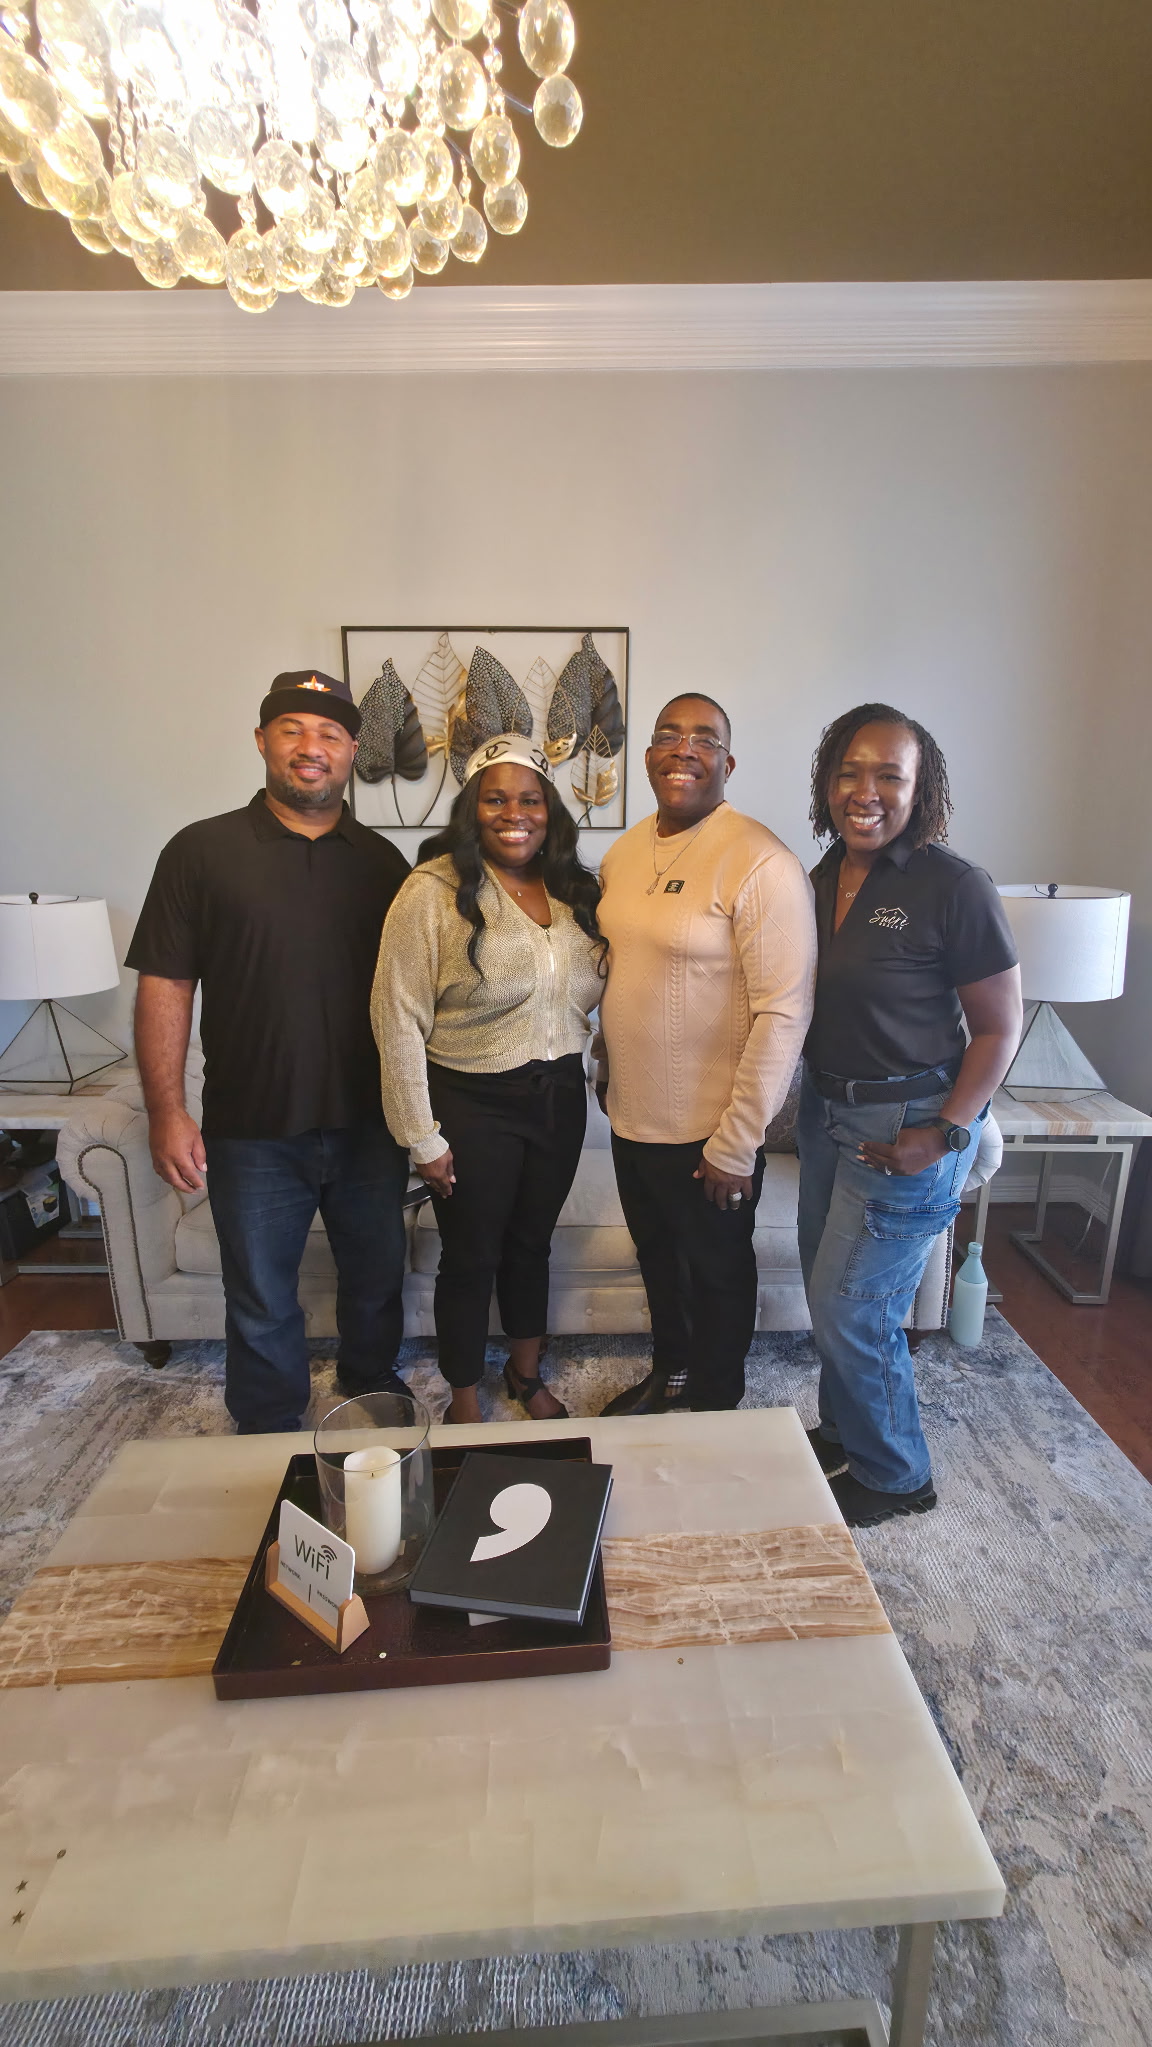
Jackie and Orlando with Patrina and Charles White
VA buyer story

Jackie and Orlando's move from Tennessee to Cypress

Jackie and Orlando are both veterans, and Jackie is also a nurse. They relocated from Tennessee and bought their home in Cypress with us. In the video below they share their experience in their own words.
Why the VA loan is worth using

What your VA home loan benefit gives you

The VA loan is one of the strongest loans available to any buyer. Here is what it does for veterans, active duty service members and eligible surviving spouses buying in the Houston area.

$0 down payment

Buy with no down payment as long as the price is within the appraised value.

No monthly mortgage insurance

Conventional and FHA buyers with small down payments pay PMI or MIP every month. VA buyers don't.

No VA loan limit

With full entitlement, VA sets no cap on the loan amount. Your lender still sets what you qualify for.

Funding fee can be waived

If you receive VA disability compensation, you pay no funding fee at all.

Reusable benefit

You can use it again after you sell, and sometimes keep one VA loan while buying with another.

Texas extras

Property tax exemptions for disabled veterans and the Texas Veterans Land Board home loan.

Start with your numbers

VA loan payment calculator for Houston

Most online calculators skip the funding fee and use the full property tax bill. This one adds the funding fee to your loan the way VA allows, and takes off the Texas disabled veteran exemption that matches your rating.

Use the rate your lender quotes you.
Houston-area rates run about 1.5% to 3.9%. Newer master-planned communities are usually higher. Every listing on HAR.com shows its rate.
Estimated monthly payment
$0
Principal and interest
Property taxes
Home insurance
HOA
Mortgage insurance$0
VA funding fee ()
Total loan with funding fee
Yearly tax savings from your exemption

Estimate only. Taxes shown before your general homestead exemption, which lowers them further after you move in and file. Your lender confirms your rate, funding fee and approval.

Want this breakdown emailed to you?

We'll send your numbers and the Texas veteran benefits that fit your situation. Patrina and Charles will follow up personally and connect you with the right VA lender for you.

Texas veteran benefits

Texas property tax exemptions for disabled veterans

Property taxes are the biggest monthly cost after your mortgage in the Houston area. Texas takes a set amount off your home's taxable value based on your VA disability rating, and veterans rated 100% (or paid at 100% for unemployability) pay no property tax on their homestead at all.

VA disability ratingTaken off your home's taxable value
10% to 29%Up to $5,000
30% to 49%Up to $7,500
50% to 69%Up to $10,000
70% to 90%Up to $12,000
100%, or paid at 100% for unemployabilityTotal exemption on your homestead

Veterans 65 or older with at least a 10% rating may qualify for the full $12,000. The 100% exemption can start the year you buy, for the rest of that year. You apply with the appraisal district (Harris County, Montgomery County or wherever the home is) using Form 50-114. Source: Texas Comptroller, October 2026.

Texas Veterans Land Board home loan

Texas veterans and military members can also get a state home loan through the Veterans Land Board, up to $832,750 with a fixed rate, and a discounted rate for a VA disability rating of 30% or higher. It works through approved lenders, so we'll connect you with one who can compare it side by side with a standard VA loan.

How a VA purchase works

Buying with a VA loan, step by step

  1. Get your Certificate of Eligibility. Your lender can usually pull it in minutes. It shows how much entitlement you have.
  2. Get pre-approved with a lender who closes VA loans often. This matters more than the rate alone. An experienced VA lender keeps the appraisal and closing on schedule.
  3. Shop with the VA appraisal in mind. VA requires the home to be safe and sound (roof, heat, water, no peeling paint on older homes). We point out problems early so they don't surprise you after the option period.
  4. Write an offer sellers take seriously. Some sellers still think VA deals are harder. We include your lender's details and a clear timeline so your offer reads as strong as a conventional one.
  5. Inspection, VA appraisal and closing. If the appraiser calls for repairs, we work them out with the seller before closing.
  6. File your homestead and veteran exemptions. After you move in, file with the appraisal district so your tax savings start.

New construction? VA loans work with most Houston-area builders. We go to the sales office with you and review the builder contract before you sign.

Where to buy

Houston-area communities our VA buyers love

We live in and focus on Northeast Houston, and we help veterans buy all over the Houston area, especially north of I-10.

Atascocita and HumbleOur home base

Lake Houston, Humble ISD, established neighborhoods and newer sections, with an easy drive to IAH.

KingwoodTree-lined and established

Trails, parks and lake access, with a mix of older homes and newer villages.

Crosby and HuffmanRoom to spread out

Bigger lots and some acreage, east of Lake Houston.

SpringNorth Houston

A wide range of prices and new construction, close to I-45 and the Grand Parkway.

CypressNorthwest Houston

Master-planned communities with newer homes and amenities.

KatyWest Houston

Popular with relocating families for newer communities and schools.

Meet your agents

Patrina & Charles White, The Luxe Duo

We're a husband-and-wife team at Sucré Realty, based in Northeast Houston. Our brokerage holds the Military Relocation Professional (MRP) certification, and helping veterans and military families buy is one of our main focuses.

Patrina served as a deputy sheriff in California before real estate, which is why we put your safety and privacy first. Charles and Patrina have been married since 2012, and we're swim and band parents raising our family here.

What working with us looks like

We only take five new buyer consultations a week, so you get real time with us and so do the clients we're already helping.

Whether you're moving here on PCS orders, transitioning out of the service or buying your next home in town, we'll walk you through your numbers, the VA appraisal and your Texas exemptions from the first call to the closing table.

Call 832-551-1005
Questions we hear most

VA home loan FAQ

How much is the VA funding fee?

For a purchase, it's 2.15% of the loan the first time you use your VA loan with less than 5% down, and 3.3% after that. Putting 5% down lowers it to 1.5%, and 10% down lowers it to 1.25%. Most buyers add it to the loan instead of paying it in cash.

Who doesn't have to pay the VA funding fee?

Veterans who receive VA disability compensation, surviving spouses who receive Dependency and Indemnity Compensation, active duty members with a Purple Heart, and service members with a disability rating issued before closing.

Is there a VA loan limit in Texas?

If you have full entitlement, VA doesn't set a loan limit. Your lender still decides how much you qualify for based on your income, credit and debts. If you already have a VA loan open, your limit depends on the entitlement you have left.

Do disabled veterans pay property taxes in Texas?

Veterans rated 100%, or paid at 100% for unemployability, pay no property tax on their homestead. Veterans rated 10% to 90% get between $5,000 and $12,000 taken off the home's taxable value. You file with your county appraisal district after you buy.

Can I use a VA loan to buy new construction?

Yes. Most builders in the Houston area accept VA loans. The home still needs a VA appraisal, and we review the builder's contract with you before you sign.

Can I use my VA loan more than once?

Yes. Your entitlement is restored after you sell and pay off your VA loan, and in many cases you can buy again with remaining entitlement while keeping your current home.

Ready to use your VA benefit in Houston?

Talk with Patrina and Charles about your numbers, your timeline and where you want to live.

Call or text 832-551-1005 Email me my numbers

VA loan and Texas benefit details summarized from the U.S. Department of Veterans Affairs, the Texas Comptroller and the Texas Veterans Land Board in October 2026 and subject to change. Only a lender can confirm your eligibility, rate and funding fee. Sucré Realty is not a lender.